Experts have underscored the need for African countries to link their instant payment systems to make cross-border transactions faster, cheaper and more accessible, in a move expected to strengthen trade, investment and remittance flows across the continent.
According to the State of Inclusive Instant Payment Systems (SIIPS) Report 2025 published by AfricaNenda Foundation, in partnership with the World Bank and the United Nations Economic Commission for Africa, the number of African countries with instant payment systems supporting cross-border transactions increased from six in 2024 to 11 in 2025.
The report indicates that Africa has 36 live instant payment systems across 31 countries which reflecting digital financial growth in the continent.
Despite this progress, fragmented payment infrastructure, inconsistent regulations, currency conversion costs and settlement challenges continue to hinder seamless transactions between African markets.
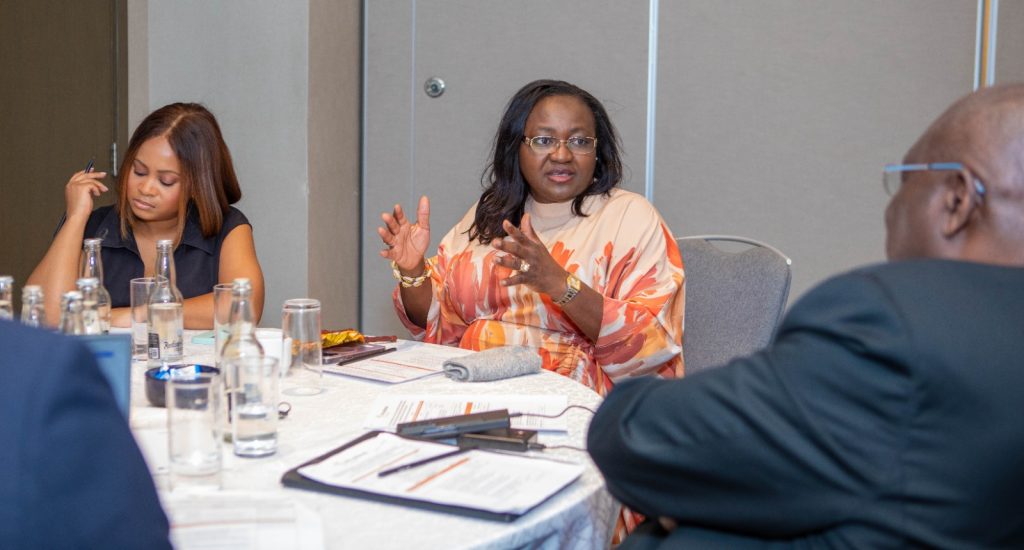
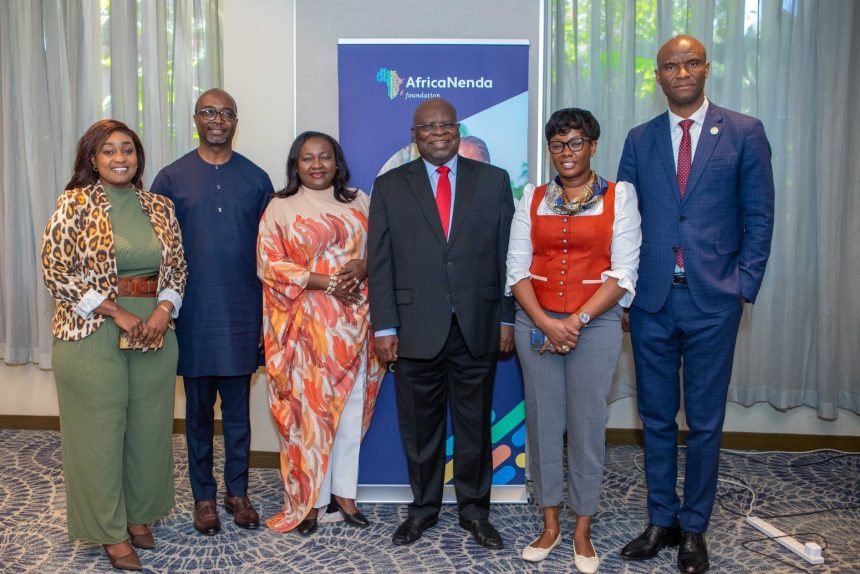
Speaking in Nairobi during a High-Level Dialogue on Regulatory Harmonization for Seamless Digital Payments, AfricaNenda Foundation, Deputy CEO Sabine Mensah, said connecting Africa’s instant payment systems could make cross-border transactions faster, cheaper and more accessible.
“Connecting Africa’s instant payment systems could make cross-border transactions faster, cheaper and more accessible, strengthening trade, investment and remittance flows across the continent,” she said.
Additionally, she stressed that interlinking these systems could enable businesses to pay suppliers across borders in near real time, help investors move funds more efficiently and allow families to receive remittances with fewer delays and potentially lower fees.
“The opportunity aligns with the African Union’s African Continental Free Trade Area (AfCFTA), which seeks to deepen economic integration by creating a single market for goods and services,” said Mensah.
She noted that the AU’s digital trade framework also promotes interoperable systems and harmonised rules to facilitate cross-border digital commerce.
However, realising this potential will require governments and regulators to harmonise payment rules, strengthen technical interoperability and improve coordination across jurisdictions. Enabling local-currency settlement could also reduce reliance on third-party currencies in eligible payment corridors.
“Payments are not the end goal,” AfricaNenda emphasises in its work on inclusive instant payment systems; they are foundational infrastructure for wider economic participation.
The next step for Africa is therefore to move beyond building national payment systems and connect them into a network that allows money to move as efficiently as goods, services and investment across the continent.